

Finding the right medical insurance for a small business in Hawaii can feel overwhelming, especially when you’re juggling multiple responsibilities as a business owner. However, securing quality healthcare coverage for your employees isn’t just a legal requirement under Hawaii’s unique Prepaid Health Care Act; it’s also a strategic investment in your company’s success and your team’s well-being. Moreover, the right insurance plan can help you attract top talent, reduce turnover, and create a healthier, more productive workplace.
Small business health insurance in Hawaii represents more than just a compliance checkbox. Indeed, comprehensive healthcare coverage serves as a powerful tool for employee retention and satisfaction. Additionally, offering quality medical benefits demonstrates your commitment to your team’s well-being, which translates into improved morale, reduced absenteeism, and enhanced productivity. Small business owners in the Aloha State must navigate specific regulations while also seeking coverage that provides genuine value for both their company and their employees.
Before diving into specific insurance providers, it’s important to understand the critical factors that should influence your decision. First and foremost, consider your employee demographics, including age ranges, family sizes, and health status, as these factors significantly impact both utilization and costs. Additionally, evaluate your budget constraints and determine how much your business can sustainably contribute toward premiums without compromising other operational needs.
Now, let’s explore each of the top 13 medical insurance providers in detail, examining what makes each option unique and helping you identify the perfect fit for your Hawaii small business.
Top 13 Best Medical Insurance for Small Business in Hawaii
Kaiser Permanente stands as one of Hawaii’s most recognizable healthcare providers, offering an integrated model that combines insurance coverage with medical care delivery. Specifically designed for Hawaii’s market, Kaiser operates its own medical facilities and employs its own physicians across the islands. This integrated approach means members receive care within Kaiser’s network of hospitals, clinics, and medical offices. The organization emphasizes preventive care and wellness programs, which can help small businesses manage long-term healthcare costs. Additionally, Kaiser’s digital platform allows members to schedule appointments, access medical records, and communicate with healthcare providers online.
Features
- Integrated healthcare system with in-house medical facilities and staff
- Comprehensive coverage including preventive care, specialist visits, and hospital services
- Multiple plan tiers ranging from bronze to platinum levels
- Access to Kaiser facilities on Oahu, Maui, and the Big Island
- 24/7 nurse advice line for medical questions and concerns
- Robust online portal for appointment scheduling and prescription refills
Pros
- Streamlined care coordination since doctors and insurance are under one organization
- No need to file claims for services received at Kaiser facilities
- Strong reputation for quality care and patient satisfaction in Hawaii
- Comprehensive preventive care programs that reduce long-term costs
- Convenient locations across multiple Hawaiian islands
Cons
- Limited to Kaiser facilities and providers, reducing flexibility
- May require referrals for specialist appointments
- Geographic limitations if employees live on islands without Kaiser facilities
2. Hawaii Medical Service Association (HMSA)
Hawaii Medical Service Association, commonly known as HMSA, represents Hawaii’s Blue Cross Blue Shield affiliate and serves as the state’s largest health insurer. HMSA has built an extensive provider network throughout the Hawaiian Islands, giving members access to nearly every hospital and most physicians across the state. The organization has been serving Hawaii residents since 1938, developing deep roots in the community and understanding the unique healthcare needs of island residents. Furthermore, HMSA offers various plan types, including HMO, PPO, and POS options, providing flexibility for businesses with diverse workforce needs. The insurer also maintains strong relationships with mainland providers, making it an excellent choice for businesses whose employees travel frequently.
Features
- Extensive network covering virtually all Hawaii healthcare providers
- Multiple plan types, including HMO, PPO, and Point-of-Service options
- Coverage extends to the mainland United States through the Blue Cross Blue Shield network
- Preventive care services are covered at 100 percent with no copay
- Virtual care options through telehealth services
- Wellness programs, including fitness discounts and health coaching
Pros
- Largest provider network in Hawaii ensures maximum choice
- Strong mainland coverage for traveling employees
- Long-standing reputation and financial stability
- Flexible plan options accommodate different budget levels
- Excellent customer service with local support teams
- Comprehensive preventive care coverage
Cons
- PPO plans can be significantly more expensive than HMO options
- Some plans require referrals for specialist care
- Premium costs tend to be higher than smaller competitors
3. UnitedHealthcare
UnitedHealthcare brings its national expertise to Hawaii’s small business market, offering comprehensive coverage options backed by one of America’s largest health insurers. Although not Hawaii-based, UnitedHealthcare has developed strong relationships with local providers and hospitals throughout the islands. The company leverages its massive national network, which proves particularly valuable for businesses with employees who travel or have family members on the mainland. Moreover, UnitedHealthcare provides sophisticated digital tools and wellness platforms that help small businesses manage healthcare costs effectively. The insurer offers various plan designs, from traditional HMOs to high-deductible health plans paired with health savings accounts.
Features
- National provider network with Hawaii-specific provider relationships
- Multiple plan designs, including HMO, PPO, and HSA-compatible options
- Advanced digital platform with mobile app functionality
- Telehealth services are included in most plans
- Wellness incentive programs to encourage healthy behaviors
- Prescription drug coverage with transparent pricing tools
Pros
- Excellent nationwide coverage for employees who travel
- Sophisticated technology platforms and mobile apps
- Strong financial backing ensures claim payment reliability
- Competitive pricing for similar coverage levels
- Extensive wellness and disease management programs
- Flexibility in plan design and customization
Cons
- The provider network in Hawaii is smaller than local insurers
- Customer service may not have deep local knowledge
- Some employees may prefer Hawaii-based insurers
4. AlohaCare
AlohaCare stands out as a Hawaii-based, community-focused health plan with deep roots in serving the islands’ residents. Originally established to serve Medicaid populations, AlohaCare has expanded to offer commercial small group coverage, bringing its mission-driven approach to employer-sponsored insurance. The organization maintains strong relationships with local providers and emphasizes culturally competent care that respects Hawaii’s diverse population. The health plan focuses on coordinated care and addressing social determinants of health, recognizing that factors like housing, food security, and transportation impact overall wellness. Additionally, AlohaCare provides personalized member support through care coordinators who help navigate the healthcare system and connect members with community resources.
Features
- Care coordination services to help navigate the healthcare system
- Culturally competent providers familiar with Hawaii’s diverse communities
- Comprehensive preventive care at no cost to members
- Behavioral health services, including counseling and substance abuse treatment
- Pharmacy benefits with preferred generic drug options
Pros
- Deep understanding of Hawaii’s healthcare landscape and culture
- Mission-driven focus on community health rather than profits
- Personalized care coordination and member support
- Competitive premiums for small businesses
- Strong relationships with local providers
- Emphasis on culturally appropriate care
Cons
- Smaller provider network compared to major insurers
- Limited name recognition among mainland transplants
- Newer to the commercial small group market
5. Aetna
Aetna offers small businesses in Hawaii access to comprehensive healthcare coverage combined with innovative wellness solutions. The company has strategically developed its Hawaii provider network to include major hospitals and physician groups across the islands. Consequently, Aetna members can access quality care while benefiting from the company’s national resources and expertise. The integration with CVS pharmacies provides additional convenience for prescription drug coverage and medication management. The insurer offers various funding arrangements, including fully insured and level-funded options, giving small businesses flexibility in how they structure their healthcare benefits. Additionally, Aetna’s commitment to transparency includes cost estimation tools that help members make informed healthcare decisions.
Features
- Growing provider network throughout the Hawaiian Islands
- Integration with CVS pharmacy locations for convenient prescription access
- Telehealth services through the Teladoc partnership
- Mental health resources, including therapy and counseling
- Diabetes prevention and chronic disease management programs
- Health coaching and personalized wellness support
- Mobile app with claims tracking and virtual ID cards
Pros
- CVS pharmacy integration streamlines prescription management
- Competitive premium rates for small businesses
- Strong emphasis on preventive care and wellness
- Innovative digital health tools and resources
- Flexible plan designs accommodate various budgets
- National network benefits traveling employees
Cons
- Smaller Hawaii network compared to HMSA or Kaiser
- May require employees to change current providers
- Less established presence in the Hawaii market
6. Humana
Humana brings comprehensive healthcare solutions to Hawaii’s small business community, focusing on value-based care and wellness initiatives. While popularly known for Medicare Advantage plans, Humana has expanded its commercial offerings to serve employers of all sizes. The company emphasizes preventive care and chronic disease management, which can help small businesses control long-term healthcare costs. Moreover, Humana’s Go365 wellness program incentivizes healthy behaviors through rewards and discounts, creating a culture of wellness among employees. The insurer has developed relationships with quality healthcare providers throughout Hawaii, though its network is more selective than larger competitors. Additionally, Humana offers innovative plan designs, including high-deductible health plans with health savings accounts, giving small businesses cost-effective options.
Features
- Selective provider network emphasizing quality over quantity
- Go365 wellness and rewards program included
- Telehealth services for convenient virtual care
- Chronic condition management programs for diabetes, heart disease, and more
- Pharmacy coverage with home delivery options
- Mental health parity with comprehensive behavioral health coverage
Pros
- Strong focus on preventive care reduces long-term costs
- Wellness rewards program motivates healthy employee behaviors
- Competitive pricing for small group coverage
- Quality-focused provider networks
- Comprehensive chronic disease management support
Cons
- A smaller provider network may limit choice
- Less established in Hawaii compared to local insurers
- May not include all preferred providers
7. Cigna

Cigna offers Hawaii small businesses access to comprehensive healthcare coverage backed by international expertise and resources. The company has strategically developed partnerships with quality healthcare providers throughout Hawaii, creating a network that balances access with cost management. Notably, Cigna emphasizes personalized healthcare through its health coaching and disease management programs, which help employees navigate complex medical conditions. The insurer’s global reach makes it particularly valuable for businesses with international operations or employees who travel extensively. Moreover, Cigna invests heavily in behavioral health services, recognizing the critical connection between mental and physical well-being. The company offers various funding options, including fully insured and self-funded arrangements with stop-loss coverage. Additionally, Cigna’s digital platforms provide transparency around costs and quality, empowering employees to make informed healthcare decisions.
Features
- Curated provider network in Hawaii with a quality focus
- International coverage for globally mobile employees
- Comprehensive behavioral health and mental wellness programs
- Telehealth services through the MDLive platform
- Health coaching and chronic disease management support
- Pharmacy benefits with mail-order prescription options
Pros
- Excellent international coverage for traveling employees
- Strong emphasis on behavioral health and mental wellness
- Sophisticated digital tools and transparency
- Personalized health coaching services
- Competitive pricing for comprehensive coverage
- Quality-focused provider networks
Cons
- Some services may require prior authorization
- Customer service is primarily mainland-based
- The network may not include all Hawaii providers
8. Oscar Health
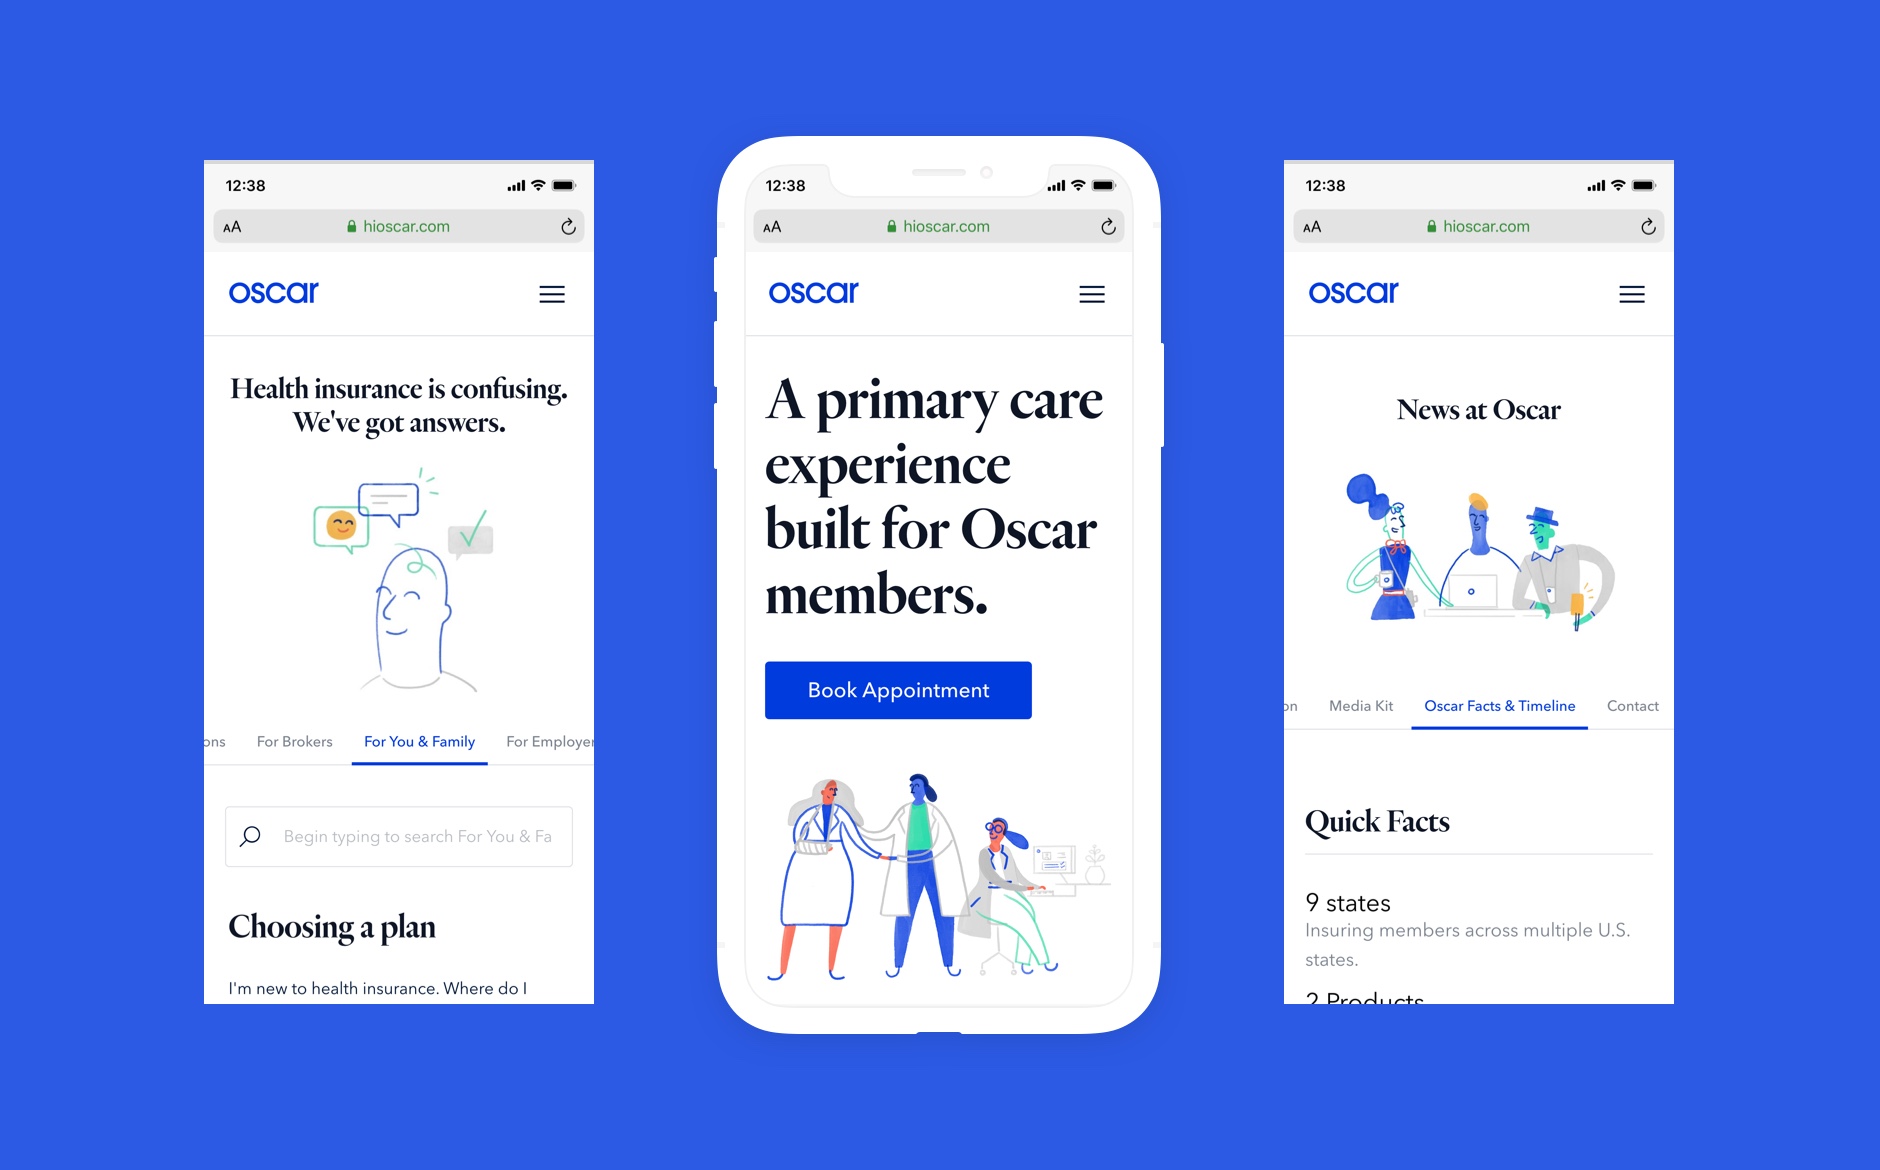
Oscar Health represents a newer, technology-driven approach to health insurance, bringing innovation to Hawaii’s small business market. Founded with the mission to make healthcare simple and transparent, Oscar leverages technology to create a more user-friendly insurance experience. The company’s mobile-first approach appeals to younger workforces comfortable with digital platforms. Consequently, members can access virtual care, find doctors, and manage their benefits entirely through the Oscar app. The insurer assigns each member a dedicated care team that includes a personal care guide who helps navigate the healthcare system and answer questions. Furthermore, Oscar emphasizes preventive care by offering financial incentives for completing health activities like annual checkups and screenings.
Features
- Technology-first approach with a comprehensive mobile app
- Telemedicine is included at no additional cost for many conditions
- Personal care guide assigned to each member for navigation support
- Step tracking program that rewards physical activity
- Cleveland Clinic health navigation for complex medical decisions
- Simple plan designs that are easy to understand
Pros
- Extremely user-friendly technology and mobile experience
- Personalized support through dedicated care guides
- Innovative wellness incentives increase engagement
- Simple, transparent plan structures
- Excellent telemedicine integration
- Appeals to technology-savvy younger employees
Cons
- Relatively new to the Hawaii market with a limited track record
- Smaller provider network than established insurers
9. Hawaii Mainland Administrators (HMA)
Hawaii Mainland Administrators specializes in serving Hawaii businesses with a unique understanding of the islands’ healthcare landscape. As a local third-party administrator, HMA offers self-funded insurance solutions that give small businesses more control over their healthcare spending. The company works with various stop-loss carriers to protect businesses from catastrophic claims while allowing them to retain savings from favorable claims experience. The administrator has developed strong relationships with Hawaii providers, creating networks that balance quality, access, and cost. Moreover, HMA offers level-funded arrangements that combine the benefits of self-funding with the predictability of fully insured plans. Their hands-on approach includes dedicated account management and personalized service that larger national carriers often cannot match. Additionally, HMA assists with compliance, COBRA administration, and other complex regulatory requirements.
Features
- Self-funded and level-funded insurance arrangements
- Local expertise in Hawaii healthcare and regulations
- Customizable plan designs tailored to business needs
- Direct relationships with Hawaii healthcare providers
- Stop-loss coverage to protect against large claims
- Dedicated account managers for personalized service
Pros
- Potential cost savings through self-funding arrangements
- Maximum flexibility in plan design and customization
- Local service with deep Hawaii market knowledge
- Transparent claims data helps identify cost drivers
- Personalized attention from dedicated account teams
- Can retain surplus from favorable claims experience
Cons
- Requires a minimum group size for self-funded arrangements
- Cash flow implications with self-funding
- More administrative complexity than fully insured plans
10. GEHA (Government Employees Health Association)
GEHA extends its federal employee expertise to Hawaii’s small business market, offering comprehensive coverage backed by decades of experience serving government workers. Although historically focused on federal employees, GEHA has expanded to provide commercial small group insurance with the same attention to value and service. The organization emphasizes straightforward benefits with comprehensive coverage and minimal exclusions. Consequently, members enjoy broad access to care without navigating complex authorization requirements. GEHA has developed a solid provider network throughout Hawaii that includes major hospitals and physician groups across the islands. Furthermore, the organization’s not-for-profit structure allows it to focus on member value rather than shareholder returns. The insurer offers both HMO and PPO-style plans, giving small businesses options based on their workforce needs and budget constraints.
Features
- Comprehensive coverage with minimal exclusions and limitations
- Both HMO and PPO-style plan options are available
- Nationwide network through partnerships with major carriers
- Preventive care is covered at 100 percent with no cost-sharing
- Prescription drug coverage, including specialty medications
- Mental health and substance abuse treatment parity
- Telehealth services for convenient virtual visits
Pros
- Not-for-profit structure focuses on member value
- Comprehensive coverage with fewer restrictions
- Competitive premiums for the coverage level provided
- Strong customer service and member support
- Nationwide network benefits traveling employees
- Stable organization with long operational history
Cons
- Less name recognition in the Hawaii commercial market
- Provider network is smaller than the local market leaders
- Limited local presence and account management
11. Ohana Health Plans
Ohana Health Plan serves as WellCare’s Hawaii operation, bringing national resources with local healthcare delivery. The organization has deep roots in serving Hawaii’s Medicaid population but has expanded to offer commercial small group coverage. The health plan emphasizes care coordination and whole-person health, addressing both medical and social factors that influence wellbeing. Furthermore, Ohana invests in community health initiatives and partners with local organizations to improve population health outcomes. The insurer offers culturally sensitive care that respects Hawaii’s diverse communities and languages. Their care management programs focus on preventive care and chronic disease management, helping small businesses control long-term healthcare costs.
Features
- Extensive provider network throughout the Hawaiian Islands
- Care coordination services for complex medical needs
- Culturally competent care teams fluent in multiple languages
- Comprehensive preventive care with no member cost sharing
- Chronic disease management programs for diabetes, asthma, and hypertension
- Behavioral health services integrated with medical care
Pros
- Strong community focus and local investment
- Extensive network, particularly with safety net providers
- Culturally sensitive care delivery
- Comprehensive care coordination services
- Competitive pricing for small businesses
- Support services beyond traditional health insurance
Cons
- May lack premium network providers in some areas
- Technology platforms are less sophisticated than competitors
- Limited brand recognition among commercial employers
12. Sanford Health Plan
Sanford Health Plan brings an innovative approach to Hawaii’s small business insurance market, combining traditional insurance with value-based care models. The organization has expanded from its mainland roots to provide medical insurance for small business in Hawaii, employers seeking comprehensive coverage with a focus on quality and outcomes. The insurer provides various plan designs, including consumer-directed health plans that pair high deductibles with health savings accounts. Furthermore, Sanford’s integrated approach connects medical, behavioral health, and pharmacy benefits for seamless care coordination. Additionally, the organization invests in telehealth and digital health solutions that increase access while managing costs. The health plan leverages data analytics to identify opportunities for improved care quality and cost management. Moreover, Sanford offers wellness programs designed to engage employees in their health through incentives and educational resources.
Features
- Value-based provider networks emphasizing quality outcomes
- Integrated medical, behavioral, and pharmacy benefits
- Comprehensive wellness programs with incentive options
- Telehealth and virtual care services included
- Health savings account-compatible plan designs
- Chronic disease management and health coaching
- Prescription drug coverage with cost transparency tools
Pros
- Value-based care approach aligns incentives for quality
- Comprehensive wellness and prevention programs
- Integrated care delivery improves coordination
- Competitive pricing with quality focus
- Strong data analytics capabilities
- Innovative approach to healthcare delivery
Cons
- New entrant to the Hawaii market with a limited track record
- Smaller provider network than established competitors
- May require provider changes for some employees
13. Mainland Medical Benefit Plan (Self-Insured Option)
Self-insured arrangements through third-party administrators represent an alternative approach for Hawaii’s small businesses seeking maximum control and potential cost savings. Rather than purchasing traditional fully insured coverage, businesses establish their own health plan and pay claims directly, partnering with administrators for network access and claims processing. This approach has become increasingly accessible to smaller employers through level-funded arrangements that provide budget predictability. Importantly, self-insured plans are exempt from certain state insurance regulations under ERISA, giving flexibility in benefit design. Businesses can customize their plans to match their workforce needs and company culture, potentially retaining surplus funds when claims are lower than expected. Many Hawaii-focused administrators specialize in helping small businesses navigate self-insurance while maintaining compliance with the state’s unique Prepaid Health Care Act requirements.
Features
- Maximum flexibility in benefit design and plan structure
- Potential for cost savings when claims experience is favorable
- Real-time access to claims data and utilization patterns
- ERISA exemption from certain state insurance mandates
- Ability to retain surplus funds from favorable experience
- Customizable wellness and prevention programs
Pros
- Greatest flexibility in plan design and customization
- Potential significant cost savings over fully insured plans
- Transparent claims data enables informed decision-making
- Ability to implement targeted cost containment strategies
- Can retain surplus from favorable claims experience
- ERISA protection provides regulatory advantages
Cons
- Requires cash reserves for claims payment
- Exposure to claims volatility despite stop-loss coverage
- More administrative complexity and responsibility